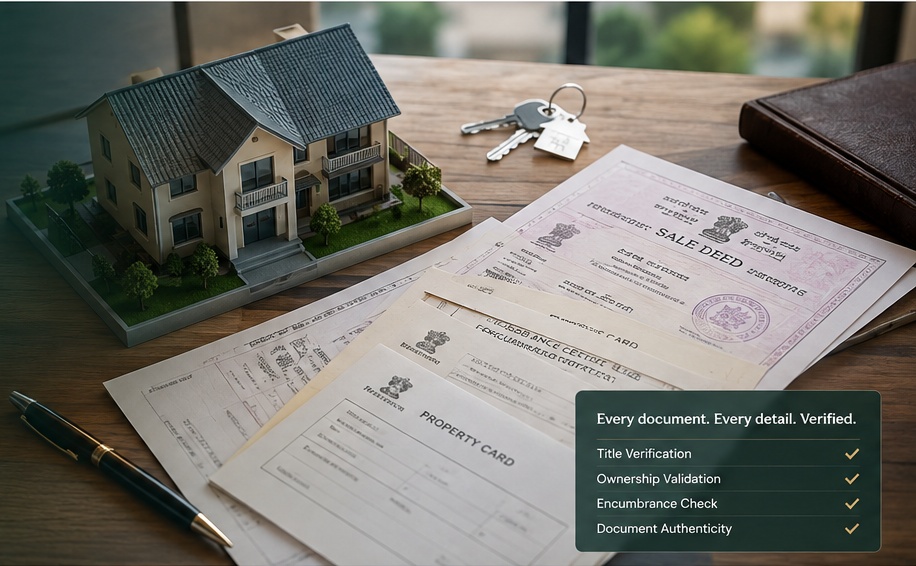
For Banks and NBFCs, NirnAI Vetting adds a Dedicated Advocate’s physical verification of original property documents to the case record, with findings recorded for review.
Each document is checked for authenticity and consistency, creating a clear record for review.
Establish document authenticity before it moves further into the lending workflow.
Know what was checked, what matched, and what needs attention before the document moves into the lending decision.
Vetting is used when the original property documents have not already been physically verified, subject to the lender’s process and the case.
It follows Legal Opinion when physical verification of the originals is required.
A Dedicated Advocate performs the original-document verification and records the findings against the case.
Material discrepancies are recorded against the case so the relevant team can review and resolve them before proceeding.
The verification findings are recorded against the case, including material discrepancies for the relevant team to review and resolve before proceeding.
Contact NirnAI to discuss how original-document verification fits the lender’s process.
Contact NirnAI